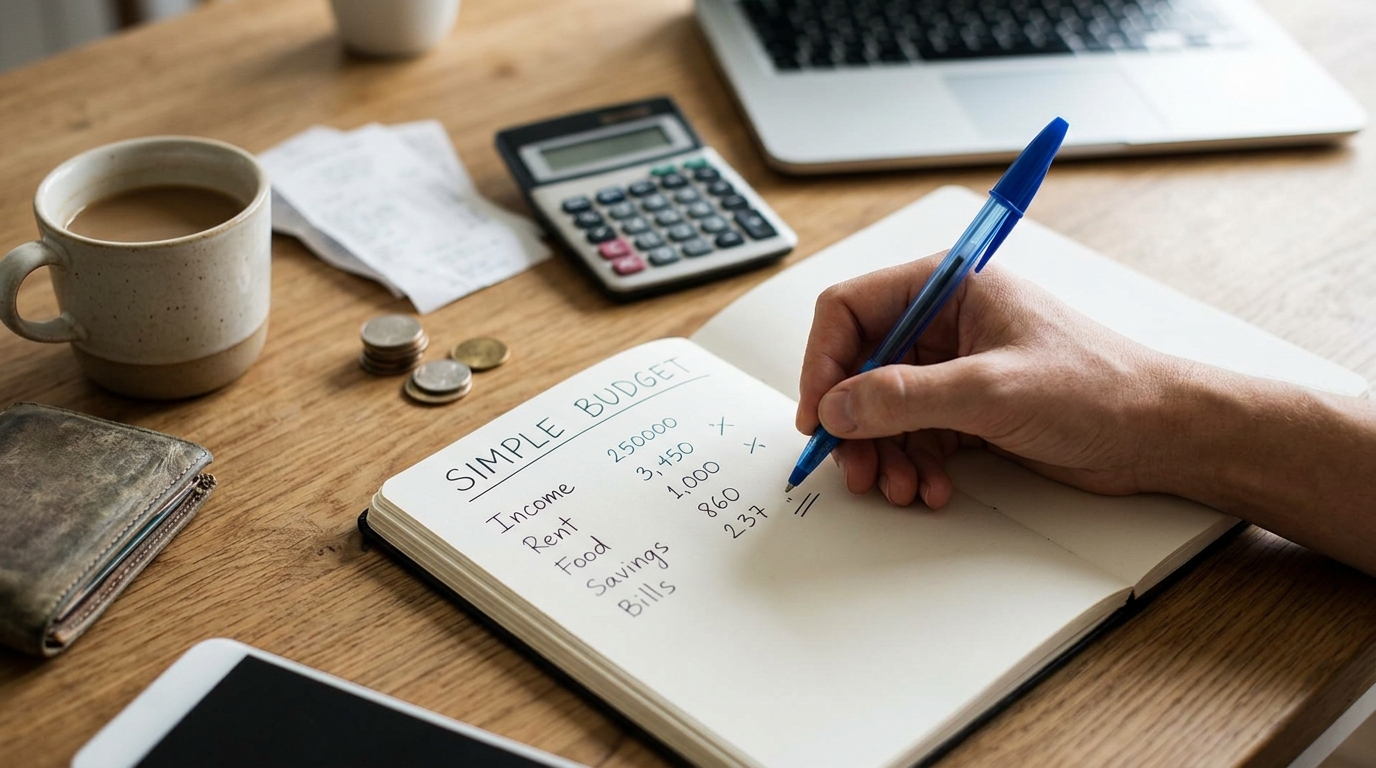
Are you tired of feeling overwhelmed by your finances? It’s time to take control and start building a simple budget for everyday life. Creating a budget doesn’t have to be complicated or intimidating – in fact, it can be quite empowering! By understanding where your money is going and setting financial goals, you can achieve greater peace of mind and financial stability. In this guide, we’ll walk you through the steps to create a budget that works for you, helping you track your expenses, save money, and reach your financial objectives. So let’s dive in and start building a budget that will set you on the path to financial success!
Importance of Budgeting
Budgeting is a fundamental aspect of financial management that plays a crucial role in achieving financial stability and success. By creating and following a budget, individuals and businesses can effectively plan and allocate their resources in a way that aligns with their financial goals. Budgeting helps in tracking income, expenses, and savings, allowing for better decision-making and prioritization of financial activities. It also enables individuals to identify areas where they can reduce unnecessary spending and increase savings, leading to a more secure financial future.
Steps to Create a Simple Budget
Creating a simple budget involves several key steps that can help individuals or businesses gain better control over their finances. The first step is to list all sources of income, including salaries, investments, or other revenue streams. Next, identify and categorize all expenses, such as fixed costs like rent or mortgage payments, utilities, groceries, and discretionary spending. Once income and expenses are identified, it’s essential to set financial goals and allocate funds accordingly. Regularly tracking and reviewing the budget is crucial to ensure it remains effective and aligned with financial objectives.
Importance of Budgeting
Budgeting is a fundamental financial practice that allows individuals and businesses to plan, track, and control their income and expenses. By creating a budget, you gain a clear understanding of where your money is going, identify areas where you can save, and set financial goals to work towards. Budgeting helps you avoid overspending, build savings, and prepare for unexpected expenses or emergencies. It also provides a roadmap for achieving long-term financial stability and security.
Steps to Create a Simple Budget
Creating a simple budget involves a few key steps. First, gather all your financial information, including income sources and expenses. Then, categorize your expenses into fixed (e.g., rent, utilities) and variable (e.g., groceries, entertainment). Next, calculate your total monthly income and expenses to determine if you have a surplus or deficit. Adjust your spending habits as needed to ensure your income covers your expenses. Finally, track your budget regularly, make adjustments as necessary, and stay disciplined in following your budget to achieve your financial goals.
Tracking Expenses
Tracking expenses is a crucial aspect of effective budgeting. By monitoring where your money goes, you gain valuable insights into your spending habits and can identify areas where you may be overspending. Utilizing tools such as expense tracking apps or spreadsheets can help streamline this process and provide a clear overview of your financial activities. Categorizing expenses, such as fixed costs (rent, utilities) and variable expenses (entertainment, dining out), can further assist in analyzing your budget allocation.
Setting Financial Goals
Setting financial goals is an essential component of budgeting as it provides a roadmap for your financial future. Whether it’s saving for a down payment on a house, building an emergency fund, or planning for retirement, establishing clear objectives can help you stay motivated and focused on achieving your desired outcomes. By setting specific, measurable, achievable, relevant, and time-bound (SMART) goals, you create a framework for success and can track your progress along the way.
Setting Financial Goals
Setting financial goals is a crucial step in achieving financial stability and success. By defining clear objectives, individuals can create a roadmap for their financial future. Whether it’s saving for a down payment on a house, building an emergency fund, or planning for retirement, setting specific, measurable, achievable, relevant, and time-bound (SMART) financial goals is key.
When setting financial goals, it’s important to consider both short-term and long-term objectives. Short-term goals can provide motivation and quick wins, while long-term goals help individuals stay focused on their broader financial aspirations. Regularly reviewing and adjusting financial goals as circumstances change is essential for staying on track and making progress towards financial independence.
Managing Income and Expenses
Effectively managing income and expenses is fundamental to successful budgeting. By tracking income sources and categorizing expenses, individuals can gain a clear understanding of their financial inflows and outflows. Creating a budget that aligns with financial goals and priorities allows for better control over spending and saving.
Managing income and expenses involves identifying areas where adjustments can be made to improve financial health. This may include finding ways to increase income through side hustles or cutting back on unnecessary expenses. By regularly monitoring income and expenses, individuals can make informed decisions that support their overall financial well-being and help them achieve their financial goals.
Managing Income and Expenses
Managing income and expenses is a crucial aspect of budgeting that requires careful planning and organization. To effectively manage your finances, it is essential to track your income sources and account for all expenses. This involves creating a detailed budget that outlines your monthly income, fixed expenses, variable expenses, and savings goals.
By categorizing your expenses and income, you can gain a clear understanding of where your money is going and identify areas where you can cut back or save more. Regularly reviewing your budget and making adjustments as needed will help you stay on track and achieve your financial goals. Additionally, implementing strategies such as automating bill payments and setting aside money for emergencies can help you better manage your income and expenses.
Tips for Sticking to Your Budget
Sticking to your budget requires discipline and commitment to your financial goals. One effective tip is to create a realistic budget that aligns with your income and expenses, making it easier to follow. Avoid overspending by tracking your expenses regularly and being mindful of unnecessary purchases.
Another helpful tip is to set specific financial goals and reward yourself when you achieve them. This can help you stay motivated and focused on maintaining a healthy financial outlook. Additionally, consider using budgeting tools and apps to help you track your spending and stay within your budget limits. By incorporating these tips into your financial routine, you can successfully stick to your budget and work towards achieving your long-term financial objectives.
Tips for Sticking to Your Budget
Consistency is key when it comes to sticking to your budget. Make it a habit to review your budget regularly to ensure you are staying on track with your financial goals. Consider setting reminders or scheduling monthly budget check-ins to keep yourself accountable. Additionally, create a system for tracking your expenses and income accurately. Utilize tools like budgeting apps or spreadsheets to make this process easier and more efficient.
Avoid impulse purchases by planning your expenses ahead of time and sticking to your budget categories. If you find yourself tempted to overspend, take a step back and reassess your priorities. Remember that staying disciplined with your budget now will lead to greater financial freedom and stability in the long run. Lastly, don’t be too hard on yourself if you slip up occasionally. Use setbacks as learning opportunities to improve your budgeting skills and make adjustments as needed.